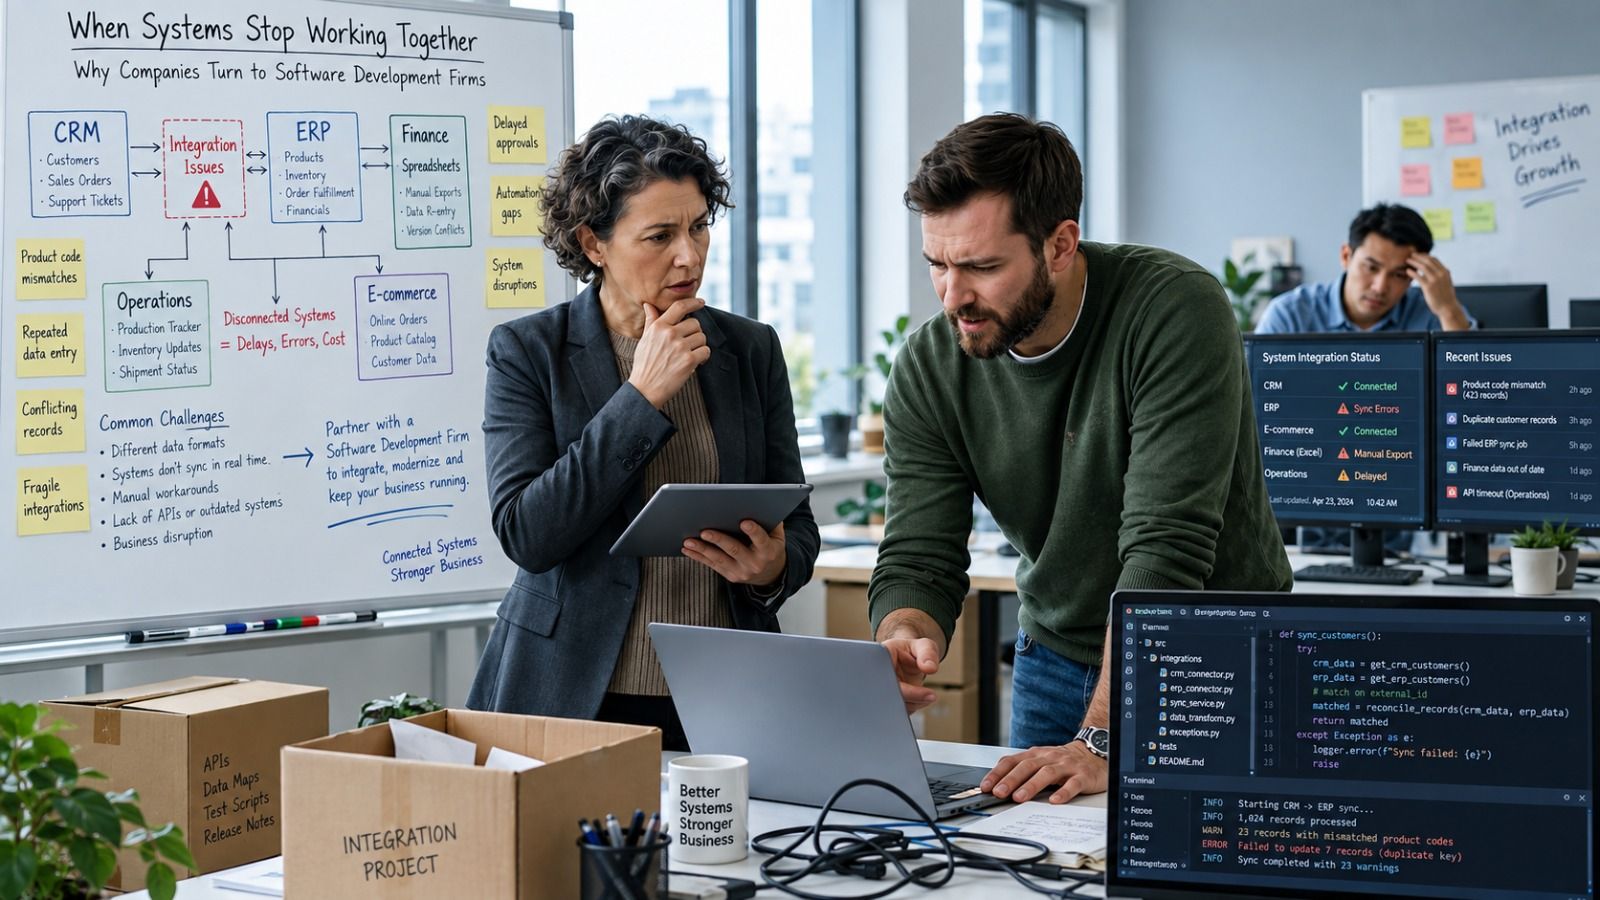


Connected insurance operations turn routine tasks into faster workflows without losing human control.
What happens when a routine policy change takes three emails, two system checks, and a supervisor’s approval? Nothing unusual, unfortunately. The same delay appears across claims, underwriting, billing, renewals, and customer support. Employees know the workarounds. Customers only see the wait.
Insurance operations automation uses workflow tools, business rules, connected data, artificial intelligence, and human review to reduce this daily drag. It does not hand every insurance decision to software. It removes avoidable copying, chasing, checking, and routing so experienced employees can focus on cases that require judgement.
Done properly, automation connects a task from beginning to end. A claim arrives, policy details are checked, documents are classified, risk flags are raised, the right handler receives the case, and the customer gets an update. Each step leaves a record. Exceptions still go to a person.
That is the basic promise of insurance intelligent operations: quicker work without losing accountability.
Swiss Re Institute’s 2025 loss estimate, reported by Reuters, put global insured natural-catastrophe losses at $107 billion. It was the sixth consecutive year above $100 billion. When claim volumes and loss costs remain high, slow internal processes become harder to carry.
What Insurance Operations Automation Actually Covers
Automation is often reduced to chatbots or robotic process automation. Both may help, but the scope is far wider. It can cover policy issuance, claims intake, underwriting referrals, document handling, fraud checks, premium reconciliation, complaints, renewals, regulatory evidence, and broker communication.
The useful question is not, “Where can we add AI?” It is, “Where does work stall, repeat, or lose reliable information?”
A motor claim offers a familiar example. The customer submits photographs and a repair estimate. An employee still downloads the files, confirms coverage in another system, copies vehicle details, emails a repair partner, and updates the customer manually. The intake looks digital. The operation behind it is not.
Insurance operations automation joins those steps into one controlled workflow. It validates required fields, matches the policy, classifies documents, runs approved checks, and sends the case to the correct queue. A handler reviews injury, unclear liability, unusual damage, or suspected fraud.
Rules Handle Repetition, While People Handle Exceptions
Rules work well when conditions are stable and visible. A document request, address update, payment reminder, or low-risk claim acknowledgement usually follows a known route.
People are still required when facts conflict, policy wording needs interpretation, or the outcome could seriously affect a customer. Poor automation tries to remove the employee. Better automation gives that employee a cleaner file and fewer administrative steps.
Where Insurance Intelligent Operations Deliver Early Value
Insurers do not need to automate their entire operating model at once. That usually creates a programme too large to govern. Early gains tend to come from narrow workflows with high volume, repeated actions, and visible service delays.
Useful starting points include:
- First notice of loss, document classification, claim assignment, and status notifications
- Policy changes, renewal preparation, payment exceptions, and broker onboarding
- Underwriting submission checks, referrals, and missing information requests
- Complaint routing, evidence collection, audit logs, and reporting preparation
Each workflow needs a named owner, a measurable baseline, an exception route, and clear stop conditions. Without those, automation simply moves confusion faster.
The UK Government’s Motor Insurance Taskforce: Final Report and Actions noted that insurers paid £3 billion in motor claims during Q3 2025, with repair costs accounting for £1.9 billion. At that scale, small improvements in triage, evidence handling, repair coordination, and customer updates can affect both service and operating cost.
Automating Claims Without Weakening Decisions
Claims are an obvious target for insurance operations automation because the process contains high volumes, many documents, and repeated customer contact. It is also where weak design becomes visible quickly.
Improve The Information Entering The Claim
A poor claim intake creates extra work later. Generic forms collect too little detail, ask irrelevant questions, or allow unreadable files. The handler then contacts the customer again before any assessment begins.
A better intake changes its questions according to the event. A water-damage claim may request the source, affected rooms, emergency action, and contractor details. A vehicle claim may ask about passengers, third parties, road conditions, and police attendance.
Insurance operations automation can check completeness, verify policy facts, identify document types, and flag urgent cases. The handler starts with a usable file rather than an electronic pile.
Keep Fraud Review Visible
Automated fraud screening can compare claim details, identify unusual patterns, and route higher-risk cases for investigation. It should not quietly reject claims because an unexplained score crossed a threshold.
Investigators need to know why a case was flagged. False positives must be tracked. Input data needs regular review, too.
Reuters reported in November 2025 that Allianz was considering reducing between 1,500 and 1,800 roles in its travel insurance division as automation and AI changed call-centre and claims work. The report shows that operational redesign affects employees as well as systems. Insurers need role planning, training, oversight, and honest internal communication alongside the technology.
Our applications and AI services help insurers modernise application estates and place governed automation inside daily workflows. We begin with the operating path because a model cannot repair unclear ownership, contradictory rules, or a broken approval route by itself.
CTA: Are Manual Claims Steps Delaying Every Customer Update?
Connect intake, document review, assignment, fraud checks, and communication with Hubops through insurance operations automation built around controlled decisions.
Using Insurance Operations Automation In Underwriting
Underwriting automation should make information easier to use, not hide how a recommendation was formed.
Commercial submissions often arrive through broker emails, spreadsheets, schedules, loss histories, inspection reports, and third-party records. Someone must organise that material before an underwriter can begin a useful analysis.
Automation can extract selected fields, compare them with appetite rules, find missing documents, and prepare a structured referral. The underwriter then reviews exposure, pricing, wording, capacity, and unusual conditions.
This is where insurance intelligent operations become valuable. The system handles preparation and routing. The underwriter retains authority over the risk.
For straightforward personal lines, agreed rules may support straight-through processing. For unusual commercial or specialty risks, quicker preparation is often a better target than automatic acceptance.
Connecting Policy, Claims, Billing, And Partner Workflows
A workflow cannot run well when its source systems disagree. Policy administration may show one address, billing another, and the claims platform an older contact record. Automation built over that conflict sends the wrong message faster.
Before scaling insurance operations automation, insurers should define which system owns every critical field. They also need controls for synchronisation failures, duplicate records, delayed updates, and manual overrides.
Two questions should be answered early:
- Which record is authoritative when platforms show different policy, payment, or claim information?
- What happens when a connection fails halfway through a customer-facing workflow?
Our discussion of why system integration projects fail and how to avoid costly delays is relevant here. Insurance workflow projects often struggle because dependencies, data ownership, security requirements, and adoption work appear too late.
For transactions involving insurers, brokers, repair networks, healthcare providers, or reinsurers, our blockchain solutions can support traceability and verified shared records where a distributed approach is justified. It is not required for every process. Where several organisations rely on the same transaction history, though, it can reduce reconciliation work.
Building Controls Into Insurance Intelligent Operations
Faster processing helps only when the insurer can explain what happened. Every automated workflow needs access rules, decision records, monitoring, exception logs, retention controls, and a human escalation path.
The European Commission Joint Research Centre’s first EU-wide survey on digitalisation at work found that 30% of workers used AI tools in 2025. Wider employee use increases the chance that unapproved tools enter regulated processes. Insurance leaders need to know which systems employees use, what information they enter, and whether outputs influence customer decisions.
Controls for insurance operations automation should include:
- Records of source data, rule versions, model outputs, employee actions, and final decisions
- Role-based access for policyholder, financial, medical, and claims information
- Testing across different customer groups, products, and claim types
- Monitoring for overrides, recurring errors, and unusual exception levels
- A manual route when data is incomplete or the workflow behaves unexpectedly
Governance is not a document stored after launch. It is part of the workflow itself.
Moving From Task Automation To End-To-End Operations
Many insurers already have small automations. A bot copies policy data. A script creates a report. An email rule forwards complaints. These tools save minutes, but they may not improve the full customer journey.
End-to-end insurance operations automation follows work across departments.
Take a missed premium payment. A useful workflow does more than send a reminder. It checks payment status, policy rules, grace periods, communication preferences, broker involvement, reinstatement conditions, and escalation requirements. It records what happened as well.
That broader design prevents the gaps customers notice. One team says a payment is missing. Another confirms it arrived. A third sends a cancellation notice anyway.
The Hubops whitepaper on architecting the agentic AI era to unlock the autonomy dividend offers useful context for insurers considering more autonomous workflows. The important step is setting boundaries before an agent can act, including approved data, permitted actions, financial limits, escalation events, and audit requirements.
Measuring Whether Insurance Operations Automation Works
Hours saved can support a business case, but that figure alone says little about customer or operational performance. Insurers should compare the workflow before and after automation.
Useful measures include processing time, queue age, rework, handoffs, customer contacts, abandoned submissions, exception volume, employee overrides, complaint rates, payment accuracy, and audit preparation time.
Insurance operations automation also needs review after launch. Products change. Fraud patterns shift. Employees find new workarounds. A rule that performed well six months ago may now create unnecessary referrals.
Reviews should include operations, technology, compliance, security, and the employees using the workflow. Dashboards can show where a queue is growing. The people handling the cases can usually explain why.
CTA: Ready To Replace Isolated Bots With Connected Insurance Operations?
Work with Hubops to map, automate, govern, and measure claims, policy, underwriting, and service workflows without losing human review.
How Hubops Approaches Insurance Operations Automation
At Hubops, we do not begin by dropping a tool into an insurer and searching for tasks it can perform. We start with the workflow as employees and customers experience it today.
We map delays, decision points, repeated data entry, exceptions, source systems, security requirements, and ownership. Then we decide what should be automated, what should be repaired first, and what should remain under human control.
Our insurance operations automation work can cover claims intake, underwriting preparation, policy servicing, document processing, fraud routing, customer communication, audit evidence, and operational reporting.
We also design for coexistence. Most insurers will run older and newer platforms together for some time. Data reconciliation, transition controls, and workflow ownership, therefore, need to be included from the beginning.
The result should not be automation theatre. It should have fewer avoidable steps, better records, shorter queues, and employees who can see what the system has done.
Final Thoughts
Insurance operations automation works best when it follows the full operating path rather than a collection of isolated tasks. The insurer needs dependable data, visible rules, sensible escalation, and people who remain responsible for difficult decisions.
Insurance intelligent operations do not remove judgement from insurance. They stop skilled employees from wasting that judgement on copying fields, chasing documents, and checking the same status on several platforms.
Start with one painful workflow. Measure it honestly. Fix its data and ownership gaps before adding more automation. Then expand from a proven operating base.
FAQs
What is insurance operations automation?
It connects workflows, rules, data, AI, and human review to reduce manual insurance administration.
Which insurance processes can be automated first?
Claims intake, document handling, policy changes, payment reminders, submission checks, and customer notifications.
Does automation replace claims handlers and underwriters?
No. It handles repeated work while specialists review exceptions and complex insurance decisions.
What are intelligent insurance operations?
They combine connected workflows, automation, monitoring, governance, reliable data, and employee judgement.
How should insurers measure automation results?
Track processing time, rework, exceptions, complaints, customer contacts, overrides, accuracy, and queue age.