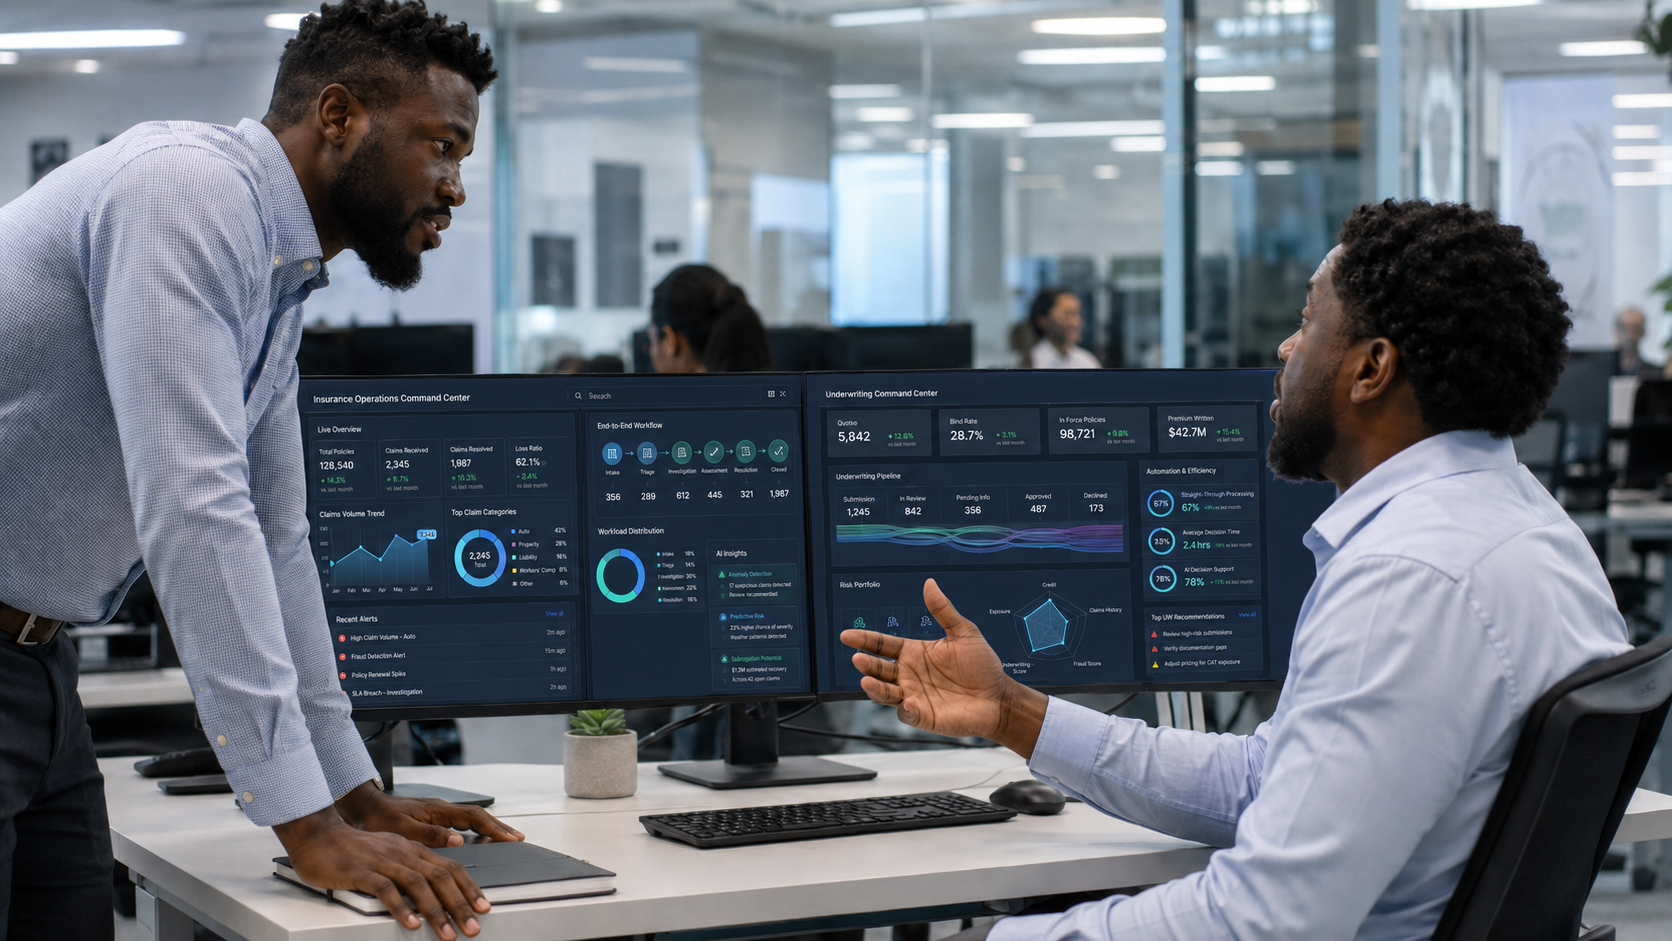


Smarter insurance operations replace manual handoffs with connected workflows built for speed and control.
What happens when a customer reports a loss in three minutes, then waits three days because the insurer still moves documents by email? That gap tells the whole story. Insurance looks digital from the outside, yet many decisions still pass through old screens, copied fields, shared folders, and manual checks.
The future will not arrive through one new portal. It will come through insurance industry digital transformation services that connect underwriting, claims, policy administration, billing, fraud checks, and customer support without making employees fight the technology. The work is less glamorous than a product launch. It is also far more useful.
For insurers, the bigger challenge is deciding what to fix first. Some teams need faster claims intake. Others need cleaner policy data, better broker connections, or fewer billing errors. The right transformation plan starts with the point where work keeps slowing down, then improves that part without creating another layer of complexity for employees.
Why Insurance Industry Digital Transformation Services Are Moving Up The Agenda
Insurance carriers are dealing with more volume, wider risk exposure, and customers who expect a quick answer. The OECD report, Global Insurance Market Trends: Preliminary 2025 Data, recorded 4.2% real growth in non-life premiums during 2025. More premium volume also sends more endorsements, claims, renewals, documents, and service requests through operations.
Insurance industry digital transformation services help carriers handle that growth without adding the same amount of manual work. A good program cuts repeated entry, gives employees one current view of the policy, and makes unusual cases easier to spot. A bad one only replaces the screen.
Underwriting Will Become Faster, But Not Fully Automatic
Underwriters rarely lose time because they cannot judge risk. They lose it while searching for missing attachments, checking outdated business details, and asking brokers to resend information. Modern underwriting removes those avoidable steps.
Submission data can be extracted, validated, enriched, and checked against appetite rules before the file reaches an underwriter. Straightforward risks may move quickly. Complex property, liability, cyber, or specialty risks still need a person who can question the information and see what the model missed.
This is where insurance consulting earns its place. It helps define which decisions can move automatically, which need review, and what evidence must be stored. Insurance industry digital transformation services should support judgment, not hide it behind a score.
Reuters reported in March 2026 that Swiss Re expects global data-center insurance premiums to reach $24.2 billion by 2030. Underwriters will need better asset, dependency, and concentration data for those risks.
Claims Work Will Be Split By Complexity
Future claims systems will sort cases by severity, evidence quality, fraud indicators, coverage questions, and customer vulnerability. Simple claims can move through validation and payment with limited handling. Large or disputed losses can be sent to experienced adjusters earlier.
Insurance industry digital transformation services can also connect photos, repair estimates, policy wording, prior losses, payments, and correspondence in one working view. That does not remove difficult calls. It removes the hunting around before a difficult call can be made.
Connected Insurance Industry Digital Transformation Services Need Better Data Flow
A customer changes an address. The policy platform records it, but billing does not. A payment posts in finance, while the service team still sees an overdue balance. These small breaks create calls, complaints, and manual corrections all day.
Insurance industry digital transformation services should begin by naming the authoritative record for customers, policies, claims, payments, and documents. Then each connected system needs a defined role. Without that decision, integration only moves conflicting information faster.
Teams dealing with this problem may use our view on how to build a strong legacy modernization strategy. It covers phased change and the choice to keep, wrap, refactor, or replace a core system.
Policy Administration Cannot Stay Isolated
Policy administration is often treated as a back-office concern. Customers feel every weakness in it. A slow endorsement, incorrect renewal document, or missed cancellation notice becomes a service issue immediately.
Modern policy operations need event-based updates, usable APIs, document controls, and cleaner links to billing and customer service. Insurance industry digital transformation services can help a carrier modernize around a stable core instead of forcing a risky replacement before the business is ready.
Health Insurance Needs Links Beyond The Payer
Health insurers deal with provider records, eligibility, authorizations, coding, claims, payments, and sensitive medical data. A delay in one part can hold up treatment or create a confusing bill weeks later.
Our work around healthcare technology transformation is relevant where payer workflows cross clinical, provider, and patient systems. Hubops can help connect data and approvals without treating health insurance as a closed administrative process.
AI in the Insurance Industry: Digital Transformation Services Need Tighter Boundaries
AI is already moving into document review, call summaries, claim triage, fraud alerts, underwriting support, and customer messaging. The pace is quick. The controls often arrive later.
EIOPA’s Generative AI Market Survey: Outlook, Use Cases and Risk Management, published in 2026, found that nearly two-thirds of 347 surveyed European insurers already used generative AI. Most remained at the proof-of-concept stage. Insurers are interested, but not ready to hand over high-impact decisions without guardrails for now.
Insurance industry digital transformation services must therefore include model inventories, approved data sources, role-based access, testing, monitoring, and human review. Every automated recommendation should have an owner. Every override should leave a record.
The Hubops whitepaper on architecting the agentic AI era goes further into permissions, machine identities, runtime controls, and intervention points. Those details become important when an AI system can do more than draft a note.
CTA: Are Your Insurance Workflows Ready For AI Decisions?
Build governed, connected insurance operations with Hubops before automation reaches high-impact policy and claims work.
Insurance Consulting Should Start With Work, Not Software
Insurance consulting should begin with a real journey. Take one commercial submission, one motor claim, or one life-policy change. Follow it from request to completion. Note every queue, spreadsheet, copied field, approval, and exception. The awkward parts usually show themselves quickly.
Insurance industry digital transformation services work better when targets are tied to that journey. Useful measures include handling time, rework, first-contact completion, leakage, error rates, and how often employees leave the main system to finish the task.
A short working list helps:
- Pick a journey with high volume or costly delay.
- Name the system of record for each key data item.
- Separate routine decisions from judgment-heavy ones.
- Test with employees who do the work every day.
- Fix exceptions before increasing the rollout.
Digital Distribution Will Become More Connected
Insurance distribution is no longer limited to an agent portal and a call center. Products are now offered through banks, retailers, travel platforms, vehicle ecosystems, employer programs, and specialist brokers. Each route sends different information to the insurer. Some submissions arrive complete. Others leave employees searching for basic details.
That creates a problem during quoting and an even bigger one later. A customer may buy through a partner, contact the insurer directly, and submit a claim through another channel. If identity, consent, product, and payment records do not line up, the service team has to rebuild the customer history by hand.
Insurance industry digital transformation services can create a shared view across direct and partner channels. They can also make product rules reusable, so the same coverage logic is not rebuilt separately for every distributor. It saves maintenance work and lowers the chance of two channels giving different answers to the same question.
Insurance consulting helps because distribution projects touch contracts, commissions, privacy, customer ownership, and service responsibility. These are operating decisions, not only technical ones. Hubops can help carriers set the workflow before new partner volume arrives.
Employee Adoption Will Decide Whether The Investment Works
A new system can pass testing and still fail during everyday use. Claims staff may keep notes outside the platform. Underwriters may download submissions because the screen hides important details. Service representatives may open several tools because no single view is dependable.
That behavior is useful feedback. It shows where the design does not match the job.
Insurance industry digital transformation services should include employee interviews, side-by-side testing, role-based training, and time to fix awkward steps after launch. Teams need to know what changed, why it changed, and where unusual cases should go. A quick demonstration is not enough.
Leaders should watch adoption closely during the first few weeks. Login counts say very little. Better signals include task completion, time spent outside the main system, repeated overrides, and how often employees create their own trackers.
These numbers show whether the process has genuinely improved. They also reveal small problems before people become used to working around them.
Climate Risk Will Push Faster Insurance Digital Transformation
Climate risk is changing property data, pricing, accumulation reviews, catastrophe response, and reinsurance decisions. Annual updates are no longer enough for locations where exposure changes quickly.
Insurance industry digital transformation services can connect geospatial information, property characteristics, inspection records, claims history, weather data, and portfolio concentration. Underwriters get a better view before renewal. Claims teams can see where damage is likely to be concentrated before reports arrive one by one.
Public insurance programs and catastrophe response also cross agency boundaries. Hubops brings useful experience from government digital modernization when insurance workflows depend on public records, identity checks, emergency services, or regulated reporting.
A Practical Roadmap For Insurance Industry Digital Transformation Services
Start with one journey that has a visible cost. Map the current steps honestly. Then fix data ownership and system connections before adding automation. Run the new flow beside the old one long enough to catch missing exceptions. After that, expand.
Insurance industry digital transformation services should move in small enough releases that teams can see what changed. Each release needs an owner, a rollback plan, and a measure that a business leader can follow.
Insurance consulting can help keep the sequence grounded. Technology teams know the systems. Operations teams know the workarounds. Compliance knows what evidence must remain. The program needs all three voices, not one department writing requirements for everybody else.
A second short checklist is worth keeping:
- Do not automate a broken approval path.
- Do not let two systems own the same field.
- Do not call a pilot successful if employees avoid it.
- Do not scale an AI tool without logs and review paths.
CTA: Still Running Claims And Policy Work Through Manual Handoffs?
Work with Hubops to redesign the flow, connect core records, and modernize insurance operations without forcing change where it is not yet needed.
Final Thoughts
The future of insurance will arrive through smaller fixes that hold: complete submissions, quicker claim routing, accurate billing updates, and AI decisions that employees can still review later.
That is the useful role of the insurance industry's digital transformation services. They connect the work behind the customer promise.
Hubops starts where data breaks, decisions wait, or employees build workarounds. We then rebuild that path in stages, with the people doing the work involved.
The strongest insurers will not own the most tools. Their people will finish work each day with fewer gaps, better records, and much less backtracking.
FAQs
What are insurance industry digital transformation services?
They connect insurance systems, data, workflows, and customer journeys across underwriting, claims, billing, policy administration, and compliance.
Where should an insurer begin its transformation?
Start with one high-volume journey where delays, repeated entry, or customer complaints create a visible operating cost.
How does insurance consulting support a digital program?
Insurance consulting links business goals, regulation, workflow design, architecture, employee adoption, and delivery priorities in one plan.
Can insurers modernize without replacing the core platform?
Yes. Stable core functions can be exposed through APIs, events, governed data services, and phased surrounding changes.
How should insurers use AI safely?
Limit permissions, approve data sources, test outputs, keep human review, monitor behavior, and store decision records.