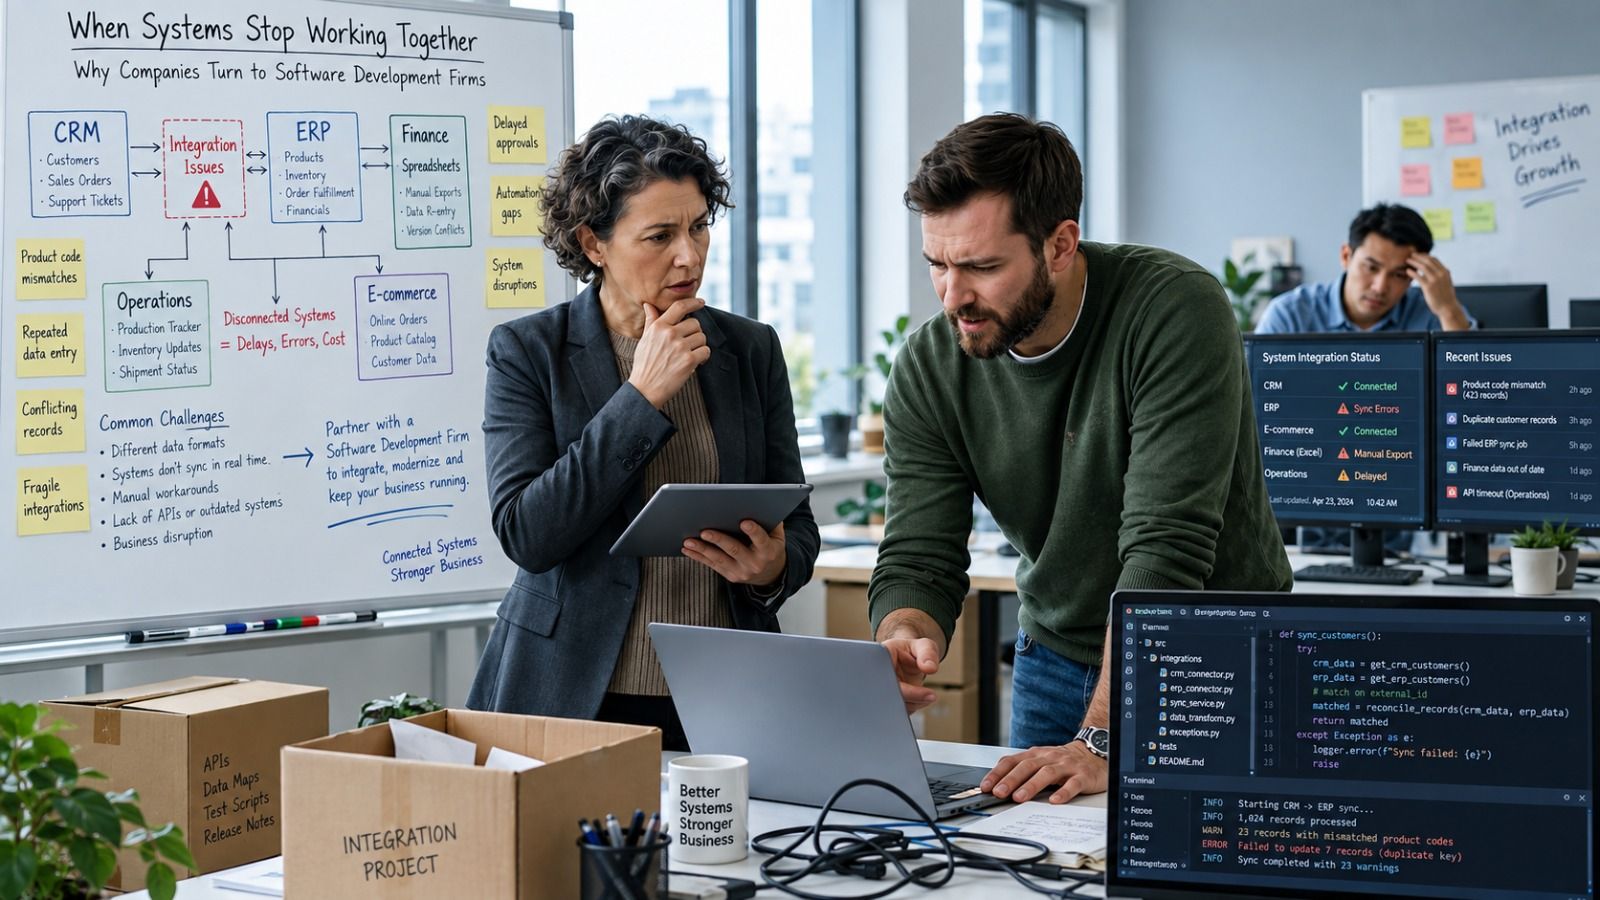
Strong platform operations turn rising policy volumes into scale without adding operational chaos.
An insurer can launch a polished customer portal and still run most of the business through email, spreadsheets, overnight batch jobs, and manual reconciliation. The customer sees a modern screen. Employees see everything happening behind it.
That gap becomes expensive as policy volumes rise. Claims take longer to assign. Underwriters wait for risk data. Finance receives figures that do not match operational records. Compliance teams spend days collecting evidence that should already exist in the platform.
Modern insurance platform operations address what happens after software goes live. They cover availability, integrations, data quality, security, release controls, vendor performance, incident handling, regulatory evidence, and the daily workflows connecting policy administration, claims, billing, underwriting, and customer service.
A capable insurance operations solution must therefore do more than process transactions. It should help the insurer increase volume without producing the same increase in manual work, operational risk, or audit effort.
Why Insurance Platform Operations Need More Attention
Insurance platforms carry long-lived products, sensitive customer records, financial transactions, claim evidence, pricing rules, and regulatory obligations. They also depend on outside parties. Brokers, repair networks, medical providers, payment processors, data suppliers, reinsurers, and cloud vendors may all exchange information with the insurer. One broken connection can affect hundreds of cases before anyone spots it.
For example, a failed document feed may leave claims handlers waiting for medical records. A delayed policy update can cause a valid customer to appear uninsured. A billing integration may complete the payment but fail to update the policy status. Each incident begins in technology and quickly becomes an operations problem.
This is why insurance platform operations cannot be treated as routine infrastructure maintenance. They influence claim response, customer retention, underwriting performance, cash movement, and regulatory exposure.
Building Insurance Platform Operations Around Business-Critical Workflows
A platform operations plan should begin with the workflows that keep the insurer functioning. Technology inventories help, but application lists alone rarely show where the actual risk lives.
Teams should map the movement of a policy, claim, payment, or underwriting referral from beginning to end. That map often reveals something uncomfortable. The core system may be stable, while the surrounding handoffs are brittle.
Identify The Workflows That Cannot stop
Not every application deserves the same recovery target. A campaign tool going offline for two hours is different from a claims intake system failing during a severe weather event.
Insurers should classify workflows by operational consequence. The review should cover:
- claim notification, triage, assignment, reserving, and payment
- policy quotation, binding, endorsement, renewal, and cancellation
- premium collection, reconciliation, refunds, and commission payments
- underwriting referrals and risk-data checks
- regulatory reporting, complaints, fraud review, and audit evidence
This gives insurance platform operations a business order. Operations teams can then assign uptime targets, recovery procedures, support ownership, and escalation routes according to actual impact.
Trace Every Important Dependency
A claims platform rarely works alone. It may depend on identity services, policy databases, document storage, payment tools, fraud models, messaging platforms, external assessors, and repair networks. Those dependencies need owners. They also need monitored service levels.
A mature insurance operations solution should show whether a transaction is completed across the full workflow, not merely whether each application is technically running. A green dashboard is not useful when customer updates are stuck in a queue nobody monitors.
Hubops has dealt with similar uptime and control demands across distributed, asset-heavy environments. Our work in utilities technology operations shows how platform monitoring, operational resilience, data movement, and incident ownership must work together when service continuity cannot be left to chance.
Scaling Claims Without Scaling Manual Work
Claims expose platform weaknesses quickly. Volumes can jump after a storm, cyber incident, travel disruption, or product recall. When the platform cannot absorb the rise, employees create workarounds. Shared inboxes fill up. Spreadsheet trackers appear. Managers reassign cases manually.
For a week, the workaround may help. After several months, it becomes part of the operating model.
Design For Event-Driven Demand
Scalable insurance platform operations need flexible processing capacity, queue management, transaction visibility, and tested fallback routes. Claims intake should be able to expand without slowing policy searches, document uploads, fraud checks, or customer notifications.
This does not mean every component must be rebuilt at once. Insurers can isolate high-volume services, move document processing outside the core, introduce event-based updates, and add capacity around the functions under the greatest strain.
Our guidance on modernising operations safely with AI-driven network modernisation explains why phased releases, rollback plans, health metrics, and controlled change are safer than replacing large operating environments in one attempt.
Remove Repeated Claim Handoffs
Automation works best when the process rules are already stable. Routine coverage verification, document classification, low-value payment approval, and customer updates may be suitable candidates.
Complex liability, injury, fraud, and high-value loss cases still need experienced review.
The goal of an insurance operations solution should not be automation everywhere. It should remove repeated handling where the decision rules are known, while giving specialists better information for cases that require judgement.
CTA: Are Claim Volumes Exposing Weaknesses In Your Insurance Platform?
Build scalable insurance platform operations with Hubops to improve workflow visibility, reduce repeated handoffs, and protect service during demand spikes.
Keeping Insurance Platform Operations Compliant By Design
Compliance becomes difficult when evidence has to be rebuilt after the event. An employee may have followed the right process, but the platform cannot show which data was accessed, which rule was applied, who approved the change, or when an exception was raised.
Modern insurance platform operations should capture those details during normal work.
The Digital Operational Resilience Act entered into application across the European Union on January 17, 2025. DORA requires covered financial entities, including insurance companies, to strengthen ICT risk management, incident response, resilience testing, and oversight of critical technology providers.
For insurers operating across jurisdictions, this creates a wider operational requirement. Technology controls, supplier records, incident logs, and recovery tests must be dependable enough for both internal management and supervisory review.
Build Evidence Into Daily Work
Audit evidence should come from controlled platform activity, not screenshots collected days before a review.
An effective setup records:
- user and service-account access
- policy-rule and pricing changes
- failed transactions and manual overrides
- deployment approvals and rollback actions
- vendor incidents and recovery performance
- data exports, retention actions, and deletion requests
These records also help operations teams. They make it easier to trace a failed transaction or determine why one policy followed a different path from another.
Treat Third-Party Platforms As Part Of The Operating Environment
Cloud providers, SaaS vendors, data partners, and specialist claims tools may sit outside the insurer’s infrastructure, but they still affect service delivery.
Vendor management should cover more than contract renewal. Teams need dependency maps, exit plans, recovery commitments, incident notification terms, data-location records, and evidence that subcontractors follow required controls.
This is one reason insurance platform operations require shared ownership. Procurement may own the contract, security may assess risk, and technology may manage the connection. Operations still need to know what happens when the service fails on a busy Monday.
Protecting Insurance Data And Platform Access
Insurance data attracts attackers because it contains identity details, financial information, health records, property data, and supporting documents. Platform expansion increases the number of access routes through APIs, customer portals, broker systems, mobile interfaces, and third-party integrations.
The NAIC 2025 Cybersecurity Insurance Report found that the number of reported cyber insurance claims rose by almost 40%, reaching nearly 50,000 claims in the reviewed period. The same report placed global cyber insurance premiums at close to $15 billion.
An insurer cannot control every external threat. It can control how access is granted, monitored, restricted, and removed.
Make Identity Controls Operational
Identity management should cover employees, contractors, partners, applications, APIs, and automated agents. Privileged access needs a stronger review because one compromised account can expose several connected platforms.
Access should also follow job activity. A claims adjuster does not need the same permissions as a platform engineer. A temporary assessor should not retain access after an assignment closes.
A secure insurance operations solution should support short-lived access, role reviews, strong authentication, transaction logging, and rapid account suspension during an incident.
Plan For Failure Before It Happens
Backups are useful only when they can be restored within the required time. Recovery plans are useful only when teams have tested them against believable failures.
Good testing includes broken integrations, unavailable vendors, corrupted records, ransomware events, sudden volume increases, cloud-region failures, and deployment errors. The objective is not to prove that the plan looks complete. It is to find where the plan fails before an actual incident does it for you.
Managing Platform Change Without Disrupting Insurance Operations
Insurers often delay platform releases because the existing environment feels fragile. The caution is reasonable. A small policy-rule change can affect quotes, renewals, broker commissions, customer documents, and reporting.
Avoiding change completely creates a different risk. Security patches fall behind. Product launches slow down. Manual work expands around platform limits.
Strong insurance platform operations create a controlled route between these two extremes.
Use Smaller Releases And Defined Rollbacks
Large releases combine too many variables. When something fails, teams spend hours deciding which change caused it.
Smaller releases reduce that search. They also make it easier to test product rules, integrations, documents, and financial outputs before wider deployment.
Each release should have:
- an accountable business owner
- documented affected workflows
- test cases based on actual insurance scenarios
- monitoring for technical and business outcomes
- a rollback trigger and named decision-maker
Hubops applies similar operational thinking in manufacturing digital transformation, where changes must improve connected platforms without interrupting critical production activity. The same principle applies in insurance. Modernisation has to move forward while daily transactions continue.
Watch Business Metrics After Deployment
Technical monitoring may show that a release succeeded. Business monitoring may show that quote completion dropped, claim assignments slowed, or payment exceptions increased.
Both views are needed.
An insurance operations solution should connect platform health to operational indicators such as claim cycle time, transaction failure rate, referral volume, policy issuance delay, payment exceptions, and customer-contact increases.
Improving Data Quality Across Insurance Platforms
Insurance platforms accumulate data over the years. Product names change. New distribution channels arrive. Acquisitions bring another set of definitions. Employees create local fields because the standard ones do not fit their work.
Soon, two systems will use different answers for the same question.
Data quality cannot be fixed through one cleansing project. It needs ownership inside the insurance platform operations. Core entities such as policyholder, insured asset, claim, broker, payment, and coverage should have agreed definitions and responsible owners.
The OECD Global Insurance Market Trends 2025 Report found that non-life gross premiums written grew by an average of 8.2% in nominal terms across reporting jurisdictions in 2024, while gross claims payments grew by 7.5%. As transaction values and volumes grow, inconsistent insurance data becomes more expensive to correct later.
A few controls make a noticeable difference:
- Assign one system of record for each core insurance entity
- Validate critical fields when data enters the workflow
- Monitor reconciliation failures instead of hiding them in monthly reports
- Review data changes when products, regulations, or distribution partners change
Our perspective on what a strong legacy modernisation strategy looks like is useful here because older platforms often need staged improvement around access, data, controls, and interfaces before replacement becomes feasible.
How Hubops Builds Insurance Platform Operations
At Hubops, we look beyond the visible application. We review the workflows, data paths, vendor dependencies, release controls, security requirements, and support arrangements that keep insurance transactions moving.
Our approach to insurance platform operations can cover platform assessment, operating-model design, workflow improvement, cloud coordination, data controls, observability, compliance evidence, release management, incident response, and ongoing optimisation.
We also help teams decide what not to change. A stable core transaction engine may remain in place while surrounding workflows, access layers, integrations, and monitoring are improved. That route is often less disruptive and easier to govern.
The result is an insurance operations solution shaped around actual policy, claim, underwriting, and compliance work rather than a disconnected list of technology upgrades.
CTA: Need Insurance Operations That Can Scale Without Losing Control?
Work with Hubops to strengthen platform reliability, compliance evidence, data quality, release controls, and daily insurance workflows.
Final Thoughts
Modern insurance does not depend on one platform alone. It depends on the system of workflows, data, people, controls, vendors, and integrations around that platform.
That wider operating system decides whether a claim moves quickly, whether an underwriter trusts the information on screen, whether a customer receives the right update, and whether an audit becomes routine work or a last-minute scramble.
Well-planned insurance platform operations give insurers room to grow without accepting more manual work, platform instability, or regulatory exposure with every new product and customer. The goal is not constant replacement. It is controlled progress, dependable service, and an operating environment that can handle what comes next.
FAQs
What are insurance platform operations?
They manage the systems, data, releases, vendors, security, support, and workflows behind insurance services.
Why do insurers need a dedicated insurance operations solution?
It helps insurers control claim volume, platform uptime, compliance evidence, data accuracy, and operational costs.
How can insurance platforms scale during major claim events?
They need flexible capacity, monitored queues, tested integrations, clear escalation routes, and reliable fallback procedures.
How does DORA affect insurance platform management?
DORA increases requirements around ICT risk, incident handling, resilience testing, third-party oversight, and operational recovery.
Can insurers modernise platforms without replacing the core system?
Yes. Insurers can improve interfaces, workflows, integrations, security, monitoring, and data controls around a stable core.