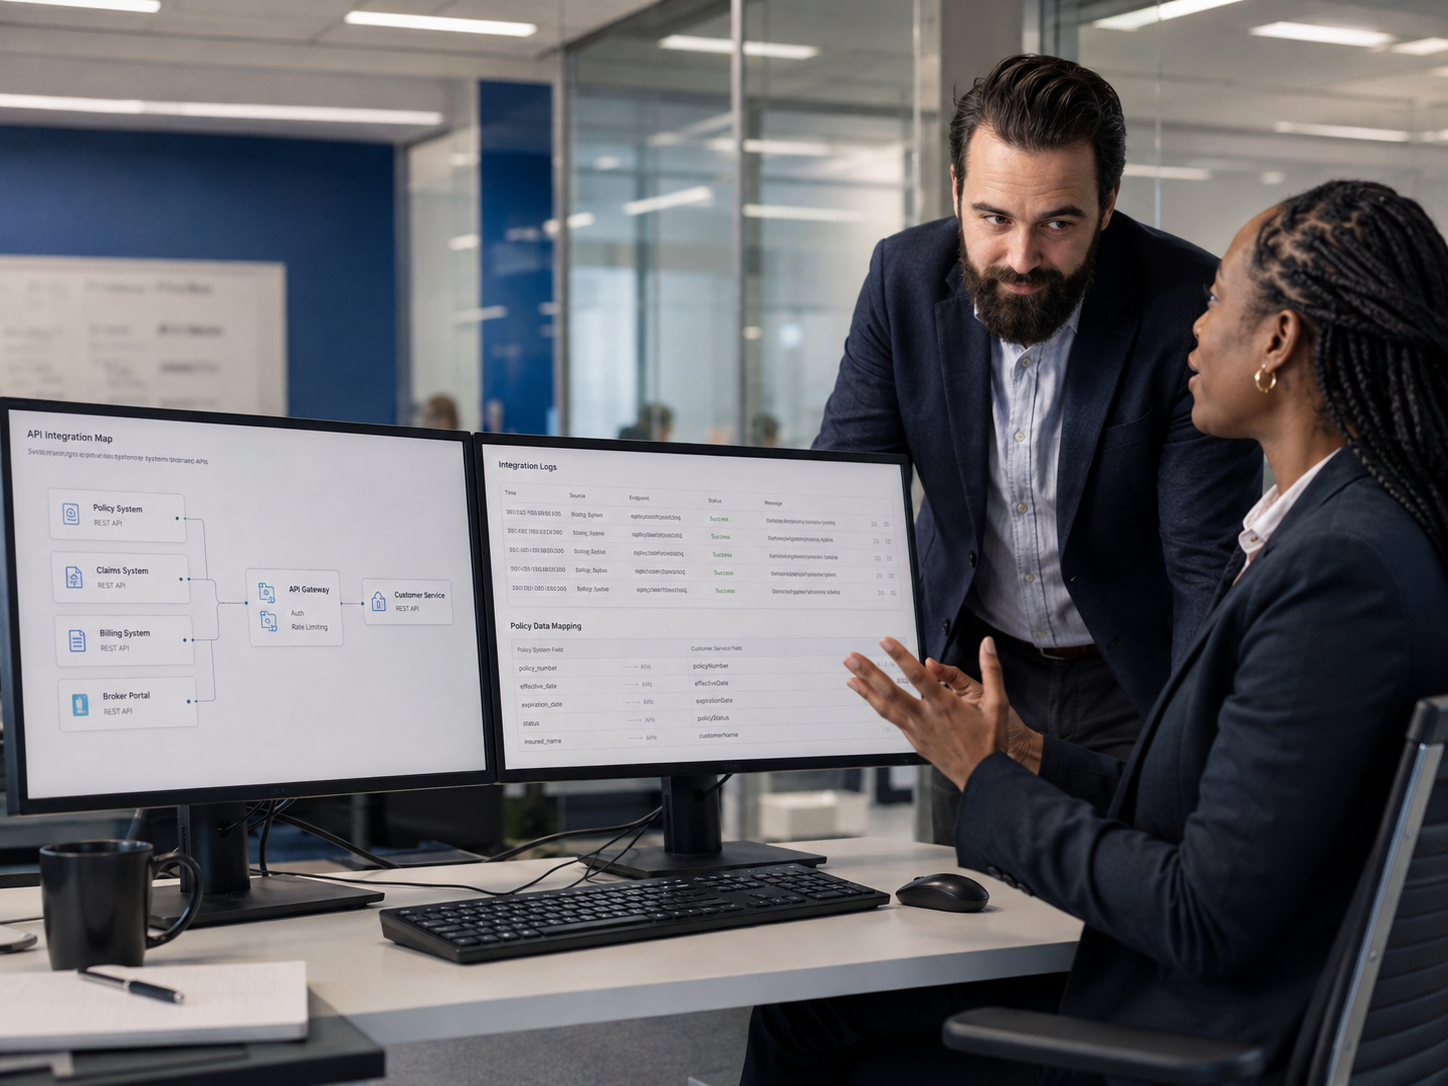


API connectivity removes the silent handoffs that slow insurance teams and frustrate customers.
Insurance operations rarely break down in dramatic places. They break in the quiet handoff.
A policy change sits in one platform. A claim note gets updated somewhere else. A broker sends a document by email. Finance waits for clean billing data. The customer, who already uploaded the same file twice, just wants a straight answer.
That is why API-based connectivity has become such a serious topic for insurers. Not because APIs sound modern. They do not win attention by themselves. They win value when they stop claims, underwriting, billing, fraud review, customer service, and partner channels from working like separate islands.
Modern insurance systems need cleaner data movement. They need safer insurance integrations. They need policy, claims, customer, payment, risk, and third-party data to move with control instead of force. For many carriers, MGAs, reinsurers, and insurtech teams, API-based connectivity is now the difference between a digital front end that only looks good and an operating model that can actually keep up.
Why API-Based Connectivity Is Now Central To Insurance Operations
Insurance has always been a data-heavy business. The difference now is speed. Customers expect instant policy access, faster quote journeys, claim status updates, digital payments, self-service changes, broker portals, and support that already knows their history.
Behind that front end, the insurer still has to protect underwriting rules, pricing logic, reserving data, compliance records, consent, document trails, and audit logs. That is where API-based connectivity becomes useful. It lets systems exchange data through controlled interfaces instead of one-off scripts, manual exports, or fragile point-to-point links.
The global insurance sector is not small enough for slow data habits anymore. The IAIS 2025 Global Insurance Market Report said its sector-wide monitoring data covers supervisors representing more than 90% of global written premiums, and it described the 2026 insurance outlook as stable despite macroeconomic and geopolitical uncertainty. That scale puts pressure on insurers to modernize without taking reckless shortcuts.
For insurance leaders, the question is no longer “Should our systems connect?” The better question is “Which connections deserve governance, monitoring, and reuse?”
That is a very different conversation.
How API-Based Connectivity Supports Insurance Integrations
Insurance integrations often begin with a simple request. Connect a claims platform to a document system. Push quote data into a CRM. Pull vehicle, health, property, payment, or identity data from a partner. Add a fraud score before claim settlement.
Then the list grows.
One team needs near-instant updates. Another team needs nightly syncs. Compliance asks who accessed which record. Customer support wants one view. The analytics team wants a clean history. Nobody wants another brittle connector that breaks during renewal season.
API-based connectivity helps by creating standard ways for systems to talk, validate, log, and recover from failures. It also gives teams a cleaner path when they add new products, channels, or partners.
Good insurance integrations usually need:
- Secure API gateways, role-based access, consent handling, and activity logs
- Reusable data contracts for policy, claims, billing, customer, broker, and risk records
- Monitoring that shows failed calls, latency, duplicate updates, and missing fields
This is not only technical housekeeping. It directly affects customer service, leakage control, turnaround time, audit response, and product speed.
Core Insurance Workflows That Benefit From API-Based Connectivity
Policy Administration And Customer Data Flow
Policy systems sit at the center of insurance, but they are often surrounded by CRM tools, broker portals, quote engines, payment systems, analytics dashboards, and document repositories. When these tools do not share clean data, teams work around the problem. They copy, check, resend, and chase.
API-based connectivity gives policy data a cleaner path across those systems. A customer address update can move from the portal to the policy system to billing and service channels without four separate manual actions. A new endorsement can trigger document generation, payment recalculation, and broker notification.
This is where Hubops' insurance capability fits naturally. Our insurance digital transformation work focuses on smarter underwriting, automated claims, and better customer journeys, which all depend on cleaner system connections.
Claims Automation And Partner Coordination
Claims bring more pressure than almost any other insurance workflow. A single claim may involve the customer, adjuster, repair partner, hospital, TPA, legal reviewer, payment team, fraud team, and reinsurer.
If those systems do not connect, the customer feels every delay.
API-based connectivity can support first notice of loss, document upload, adjuster assignment, damage review, fraud scoring, approval routing, payment release, and status updates. It also helps insurers bring partner data into the claims process without opening the whole core platform.
Reuters reported in March 2026 that U.S. hospitals and insurers were both leaning on AI for coding, billing, payment review, and claims scrutiny. The same report said health systems spent about $1 billion on AI in 2025, while insurers spent about $50 million, based on Menlo Ventures data. That gap shows why insurers need stronger integration foundations before AI becomes another disconnected layer.
AI can help with claims. But poor connections can still slow the file.
Underwriting, Risk Data, And External Sources
Underwriting has moved far beyond static forms. Many insurers now pull from credit data, property data, vehicle data, health information, geospatial inputs, weather feeds, IoT signals, and partner records. The value is not in collecting more data. The value is in using reliable data at the right step.
API-based connectivity lets underwriting teams bring external data into rating and decision workflows with more control. It can also keep records traceable, which helps when underwriters need to explain decisions.
This is especially important for insurance integrations that touch regulated or sensitive data. A fast connection with weak governance creates risk. A slower but traceable connection usually serves the business better.
Teams exploring AI-assisted underwriting should also review how data enters, moves, and gets checked before it reaches decision logic. Hubops covers this kind of workflow risk in how to add AI to business applications without breaking workflows, where the focus stays on data boundaries, human review, and safe integration paths.
Why Older Insurance Systems Struggle Without API-Based Connectivity
A lot of insurance technology still works, but not gracefully.
Many core platforms were built for internal users, batch updates, and controlled office workflows. They were not designed for embedded insurance, real-time quote journeys, omnichannel service, instant claims status, or partner ecosystems.
That does not mean every system needs replacement. Full replacement can be expensive, slow, and risky. But keeping older systems untouched creates its own cost.
API-based connectivity can act as a controlled layer between older core systems and newer digital channels. It lets insurers expose selected functions without giving every new tool direct access to the core. It also supports staged modernization, where teams improve high-value workflows first.
The IAIS 2025 Global Insurance Market Report also said that reported gross reinsurance premiums reached almost $1.75 trillion in 2024, representing about 23% of total global gross written premiums. That level of dependency across carriers, reinsurers, and risk transfer markets makes clean data exchange more than a back-office preference.
When a claim, exposure, treaty, or bordereau file moves late or moves wrong, the downstream impact is not small.
Building API-Based Connectivity Without Creating API Sprawl
More APIs do not automatically mean better architecture. In fact, some insurers create a new problem while trying to solve the old one. Every team builds its own connector. Naming rules differ. Authentication changes by vendor. Nobody owns versioning. Documentation falls behind.
That is API sprawl, and it can become just as messy as manual work.
A cleaner approach to API-based connectivity starts with business workflows, not endpoints. Claims first. Then policy. Then billing. Then partner data. Each API should have an owner, a use case, a data contract, security rules, and monitoring.
The most useful questions are direct:
- Which data must move instantly, and which data can move in batches?
- Which systems are sources of truth, and which systems only consume data?
- Which insurance integrations carry personal, financial, medical, or claim-sensitive data?
- What happens when an API call fails during a live customer journey?
These questions keep the architecture honest.
Hubops also supports regulated financial environments through banking and financial transformation, where security, auditability, compliance automation, and data control sit close to every workflow. Insurance teams face many of the same pressures, especially when payments, identity, fraud, and customer servicing overlap.
API-Based Connectivity And The Future Of Insurance Platforms
The future insurance platform will not be one giant system. It will be a connected operating layer across core platforms, cloud services, AI tools, partner networks, analytics, and customer channels.
That future needs API-based connectivity because insurers will keep adding new data sources and new service models. Embedded insurance needs partner APIs. Usage-based insurance needs sensor and telematics flows. Claims automation needs document, payment, repair, and fraud integrations. AI-assisted service needs a clean customer history and safe action controls.
Allianz Research’s Global Insurance Report 2026 projected the global insurance market to expand at an annual rate of 5.3% over the next decade, with health insurance expected to grow 6.7% annually. Growth like that will not be served well by disconnected systems and slow handoffs.
There is also a wider economic pressure. Reuters reported on July 8, 2026 that the IMF lowered its 2026 global growth forecast to 3.0% and expected 2027 growth at 3.4%. In that kind of environment, insurers have to improve cost control without weakening service. Better connectivity is one of the cleaner ways to do that.
How Hubops Helps Insurers Plan Better Insurance Integrations
Hubops looks at connectivity as an operating problem first. We do not start by adding connectors everywhere. We look at the workflow, the data ownership, the failure points, the controls, and the outcome the insurer wants.
For example, a claims leader may want faster settlement. The real blocker may be document routing, payment approval, adjuster assignment, or fraud review data. A distribution team may want a broker portal. The blocker may be product data, quote rules, or poor CRM sync. A CIO may want AI in underwriting. The blocker may be inconsistent data access across policy, claims, and third-party systems.
API-based connectivity helps when it is tied to that level of diagnosis.
Hubops can support insurers with API architecture, secure integration layers, cloud-ready data flow, partner connectivity, AI-ready workflow design, and monitoring. Our guide on how to prepare your data stack for AI at scale also fits this work because insurance AI depends heavily on governed, accessible, and repeatable data.
CTA: Need Insurance Systems That Stop Slowing Each Other Down?
Build connected policy, claims, billing, fraud, and partner workflows with Hubops so teams can reduce manual fixes, improve service speed, and keep data safer.
Practical Steps Before Starting An API-Based Connectivity Program
A good connectivity program does not need to start big. It needs to start correctly.
First, map the workflow that creates the most visible pain. Claims delay. Quote abandonment. Billing disputes. Broker servicing. Policy changes. Pick one. Then list every system, field, approval, and person involved. That map will show where the data gets stuck.
Second, define the source of truth. Many insurance integrations fail because three systems believe they own the same customer, policy, or claim record.
Third, separate high-risk data from ordinary workflow data. Medical details, payment data, identity data, and claim evidence need stricter access and logs.
Fourth, design for failure. APIs fail. Vendors go down. Fields change. Networks slow. Good architecture plans for retries, queues, alerts, and fallback paths.
Fifth, write documentation that people will use. Not a 90-page file nobody opens. Short API descriptions, owner names, data fields, error rules, and change notes.
API-based connectivity works best when business teams and technical teams share the same map. Otherwise, IT builds the connection, and operations invents the workaround.
CTA: Ready To Connect Insurance Workflows Without Rebuilding Everything?
Use Hubops to plan secure API-based connectivity across core platforms, digital channels, partner systems, and AI-ready data flows.
Final Thoughts
Insurance customers do not care which system failed. They only see a delayed claim, a repeated form, a missing update, or a support agent without the full record.
That is why API-based connectivity deserves a serious place in the modernization plan. It helps insurers connect the work behind the promise: policy service, claims, underwriting, billing, fraud, compliance, and partner delivery.
The best insurance integrations are not noisy. They are stable, traceable, secure, and easy to reuse. They let teams add new channels without breaking old workflows. They let AI tools access cleaner data without bypassing controls. They let leaders modernize in stages instead of gambling on one huge rebuild.
For insurers planning the next move, API-based connectivity is not just a technology choice. It is the foundation for faster service, cleaner operations, and systems that can grow without creating fresh chaos every quarter.
FAQs
What is API-based connectivity in insurance?
API-based connectivity in insurance means using controlled APIs to connect policy, claims, billing, customer, partner, and analytics systems.
Why do insurers need better insurance integrations?
Insurers need better insurance integrations to reduce manual updates, improve claims speed, protect data, and support cleaner customer service.
Can API-based connectivity work with older core insurance systems?
Yes. API-based connectivity can expose selected functions from older systems while protecting the core through gateways, rules, and monitoring.
How does API-based connectivity support claims automation?
It connects FNOL, documents, adjusters, fraud checks, approvals, payments, and status updates so claims move with fewer manual delays.
How should an insurer start an API-based connectivity project?
Start with one painful workflow, map systems and data owners, define security rules, then build reusable APIs around that path.